
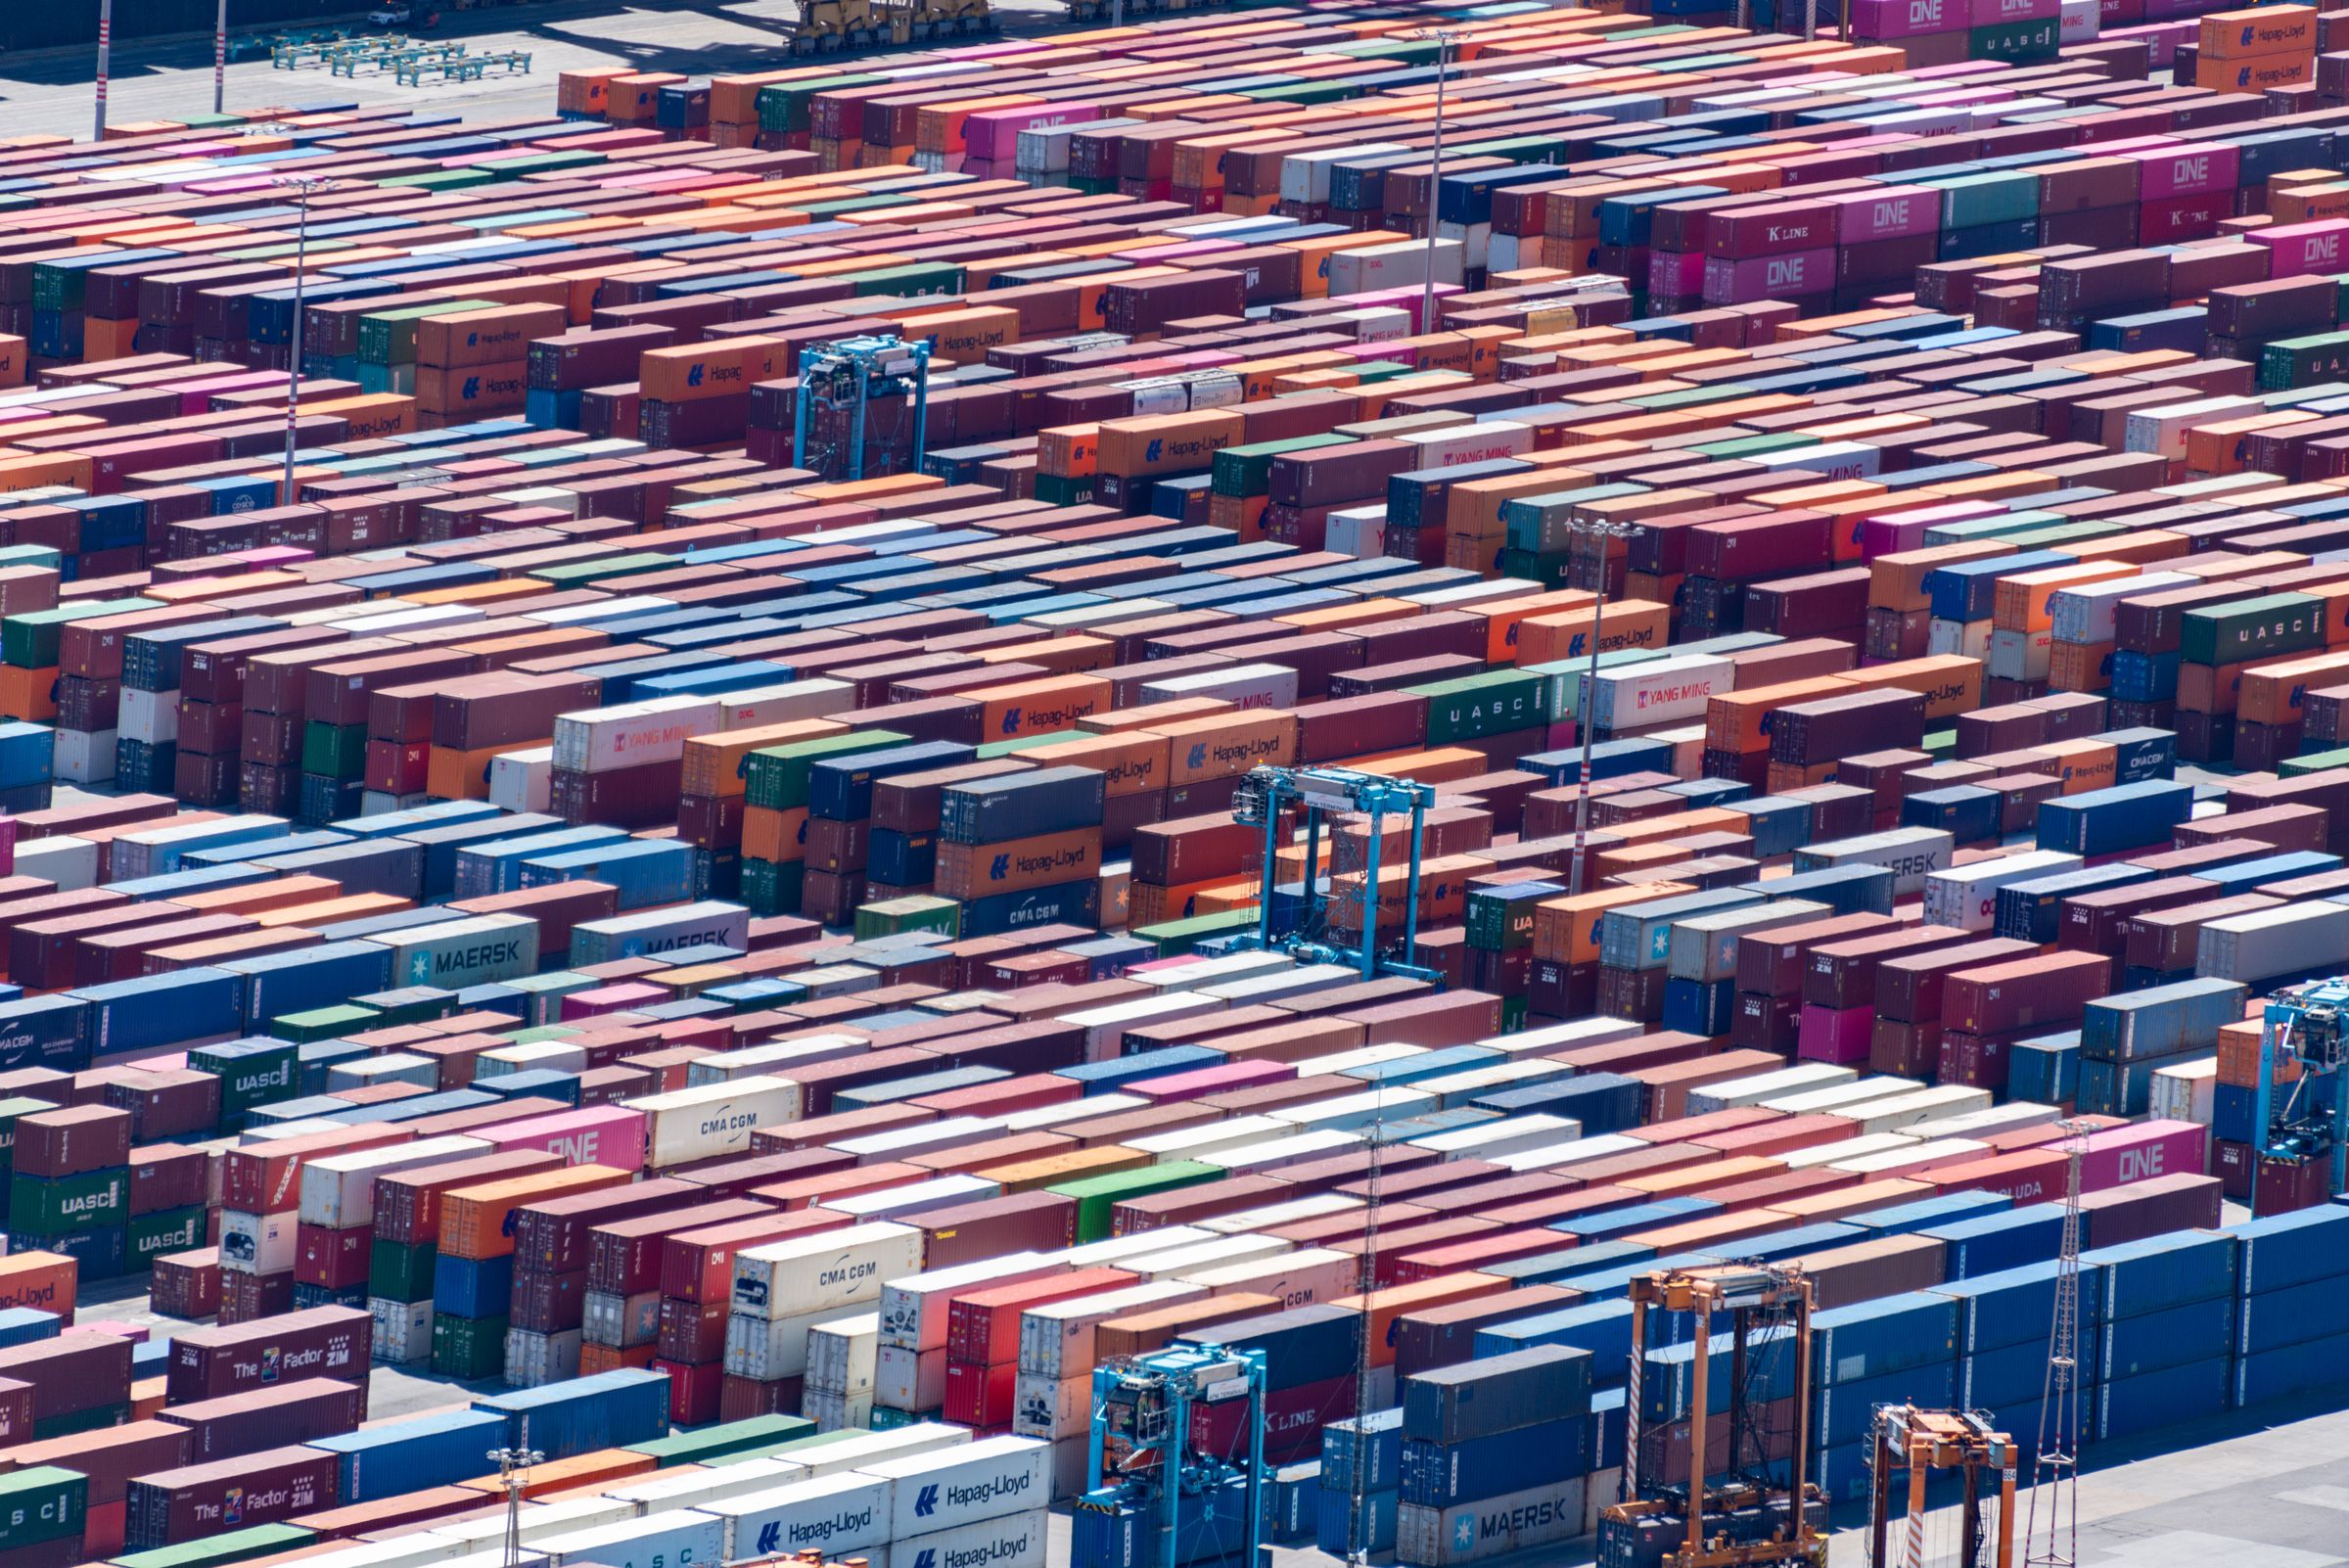
Consider a hypothetical MGA whose marine portfolio has expanded through a new distribution relationship. Premium is up. Retention looks healthy. The underwriting team still describes the business as cargo. Yet the new accounts carry different commodities, spend longer in storage and concentrate at fewer terminals. The class label has stayed the same; the proposition presented to capacity providers may not have.
That is the question behind an apparently straightforward growth result: has the MGA written more of the business it understands, or has it become a different business? The answer does not appear automatically in premium growth, average rate change or a reassuring aggregate loss ratio. Each can conceal a shift in the composition of the book.
The task is not to freeze the portfolio. It is to make consequential changes visible while leadership still has choices about price, terms, distribution and capacity. Growth becomes more credible when management can explain what changed, why it changed and what evidence would cause it to reconsider.
The market is changing more than price
Marsh’s Global Insurance Market Index reported a 6% decline in global commercial insurance renewal rates in the second quarter of 2026. Its property measure fell 12%, while casualty rose 2%. The report also described competition through broader coverage, higher limits and reduced retentions. These are averages reflecting Marsh’s client portfolio, not benchmarks for an individual MGA.
The important implication for a leadership team is not that its own rate should match the index. It is that price and the scope of the promise can move together. Holding premium flat while accepting a lower attachment point or a broader coverage grant is not necessarily holding the economics flat. A rate-change number needs a clear definition of what was held constant.
Nor is all exposure growth evidence of commercial success. An increase in insured values may raise premium without adding customers. A new producer may bring accounts that look familiar by industry code but differ in operations or loss potential. A larger average policy can reflect higher limits rather than stronger pricing. Management needs to separate these explanations before selecting a response.
An improving average can tell the wrong story
Consider a second, simplified illustration. In period one, a portfolio has $80 million of earned premium in segment A at a 50% loss ratio and $20 million in segment B at an 80% loss ratio. Total losses are $56 million against $100 million of earned premium, producing a 56% aggregate loss ratio.
In period two, segment A expands to $110 million and its loss ratio worsens to 52%. Segment B contracts to $10 million and its loss ratio worsens to 82%. Total losses are now $65.4 million against $120 million of earned premium. The aggregate loss ratio improves to 54.5%, even though both segments deteriorate. Premium has grown 20%, and the headline ratio has improved by 1.5 percentage points.
There is no accounting trick in that result. The portfolio contains more of the lower-loss-ratio segment. The mix shift could be a good decision, but it does not demonstrate better performance within either segment. A board that rewards the aggregate improvement without asking about composition could miss two emerging problems.
The figures are an MGA Index illustration, not observed market data. They assume comparable, fully developed loss ratios and earned premium for two distinct periods, with no expense or reinsurance effects. Real reviews must also account for claims maturity, reserve changes and the timing of premium earning. A simple example isolates the mix effect; it does not replace actuarial analysis.
Use two views of the book
One view should show the portfolio as it actually exists. That is the business management must fund, service and explain to its partners. The other should show performance on a suitably comparable basis, so changes in composition do not masquerade as changes in underwriting quality. Neither view is sufficient alone.
In a 2025 CAS Forum paper, Mark Shapland and Trevor Parish examine how changes in business mix affect observed premium and loss trends. Their methodology uses granular rating information to help distinguish mix effects from underlying trends. Importantly, the paper uses fictional data to illustrate the method and identifies practical limits, including the need for detailed policy information. It is methodological evidence, not a study showing how much leakage occurs across MGAs.
For management, the application starts with stable definitions. Compare relevant cohorts by business type, geography, limits, deductibles or attachments, producer and underwriting period. Have actuarial colleagues identify which comparisons are credible. New segments with little experience should remain visibly uncertain, rather than being assigned the reassurance of an established portfolio average.
Avoid treating every movement as an independent additive explanation. A new producer may simultaneously change geography, account size and coverage. Attributing the full effect to each dimension would count the same change several times. The purpose is a reconciled account of growth, not a dashboard with more plausible labels than evidence.
Sometimes the relationship changes, not just the risks
Markel’s second-quarter 2026 filing offers a different example of why premium requires context. Its Hagerty business moved to a fronting arrangement from January 1, 2026. Markel reported $598.1 million of first-half fronting premium attributable to Hagerty, all ceded to Hagerty Re. Before the transition, most, but not all, of that business had been ceded.
This is not an example of hidden deterioration. It is a disclosed change in economic structure. It shows why even a familiar program and brand can require a different reading of reported volume. MGA leaders should be equally explicit when their own retention, commissions, risk sharing or capacity arrangements change. The underwriting story and the fee-income story should not be confused.
Make portfolio change a decision, not a discovery
At the next operating review, select the largest source of growth rather than reviewing every segment superficially. Reconcile the increase into renewals, new business, price, exposure and coverage changes, using a documented method that avoids double counting. Identify cancellations and non-renewals as well. What left the book can matter as much as what entered.
Then ask the underwriting leader to explain the material changes in risk characteristics. For the illustrative cargo book, that could include commodities, maximum values at a location, storage duration and shared routes or terminals. For another class, those fields will be different. The point is to examine the variables that could alter the loss outcome, not to impose a universal scorecard.
Ask distribution leaders to connect those changes to producer behavior. Did a new channel bring business the team deliberately sought? Did the conversion rate rise because service improved, because competitors withdrew or because terms became easier? Those explanations have different implications for whether growth is repeatable.
Finally, assign an owner and a review date to any material uncertainty. A decision may be to continue growing, obtain better information, limit a concentration or change terms within the MGA’s authority. The useful output is a reasoned action, including a reasoned decision not to act. It is not a blanket rule that every departure from last year’s mix must be reversed.
The counterpoint: a different book may be a better book
An MGA may intentionally move toward a segment where it has stronger expertise, better distribution or a more attractive risk-adjusted proposition. Penalizing every mix shift would discourage exactly that kind of underwriting judgment. Historical stability is not the objective.
The distinction is between deliberate change supported by evidence and unexamined change explained after the fact. The former has a thesis, a capacity discussion, appropriate authority and a plan for testing results. The latter relies on an aggregate number to reassure people who have not yet asked what sits inside it.
A strong growth presentation should answer two questions separately: did we improve the business we already had, and did we choose well when changing the business we now have? When leadership can answer both, premium growth becomes the beginning of a substantive discussion rather than its conclusion.
Research note: this article combines public market commentary, actuarial methodology and a company filing. They cover different populations and purposes and are not a common dataset. The scenarios and proposed management review are MGA Index analysis. No interviews or private portfolio data were used.
Questions for the room
- Which risk characteristics changed most within our largest source of growth?
- Does the aggregate result improve because cohorts improved, because the mix changed, or both?
- Can we explain rate movement without confusing it with changes in coverage or exposure?
- Which changes were deliberate, who approved them and what would challenge the thesis?
Sources and methodology
This analysis draws on the public sources below. Company-specific disclosures are treated as examples, not market-wide evidence. Interpretation is MGA Index’s own.
1 Marsh: Global Insurance Market Index, Q2 2026, including methodology caveats 2 Shapland and Parish: Improving Trend Estimation Using Mix of Business Data, CAS Forum (2025) 3 Markel Group: Q2 2026 Form 10-Q, Hagerty fronting transitionMGA Index Newsroom
The MGA Index Newsroom produces independent reporting and analysis for leaders across the delegated insurance market. Our work connects public evidence to the operating and strategic decisions facing MGA leadership teams.
Newsroom analysis distinguishes reported facts from interpretation and identifies the public sources supporting material claims. Relevant relationships or potential conflicts are disclosed with the coverage.
Editorial standards and corrections